

Kenya has formally exited the COMESA Sugar Safeguard regime after it lapsed on November 30, 2025, marking a decisive transition for the nation’s sugar sector.
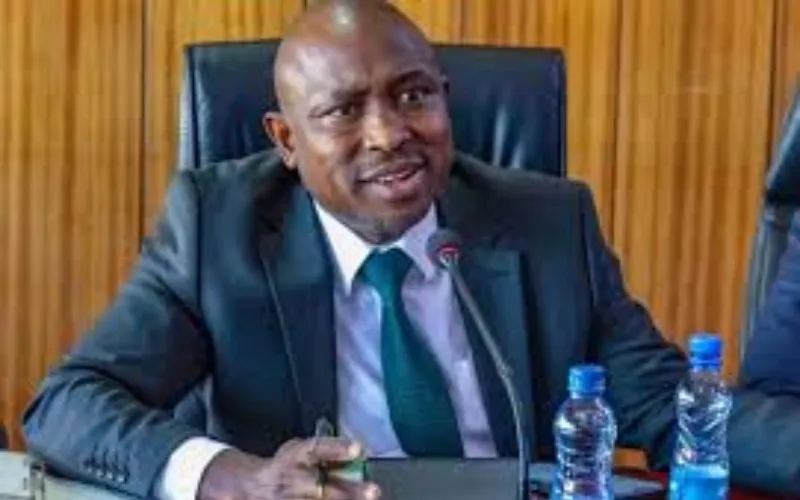
In a statement, the Kenya Sugar Board CEO Jude Chesire explained that after 24 years in the safeguard, it had fully achieved its objective as a temporary, reform-driven instrument to stabilize and restructure the industry.
Chesire reassured stakeholders in the sugar sector that Kenya’s exit was a show of strength and not vulnerability, adding that there would be no disruptions in operations.
“Kenya’s sugar industry is stable, well-managed, and supported by clear policy direction. Farmers, millers, workers, and investors are assured that the exit from the safeguard does not expose the sector to disruption, but rather signals readiness to compete within a structured and fair regional market,” he stated.
The CEO elaborated that over the past several years, the Kenya Sugar Board under the Ministry of Agriculture and Livestock Development, has deliberately shifted policy focus in the sugar industry from protection to competitiveness anchored on value addition, efficiency, and diversification.
“Globally, sugar is no longer treated as a single commodity. In competitive markets, sugarcane is primarily an industrial raw material, with refined sugar increasingly becoming a secondary product,” he remarked.
Formed in 1994, COMESA (Common Market for Eastern and Southern Africa) consists of 21 countries and its main focus is to promote trade among member states and beyond. The trading block forms a major marketplace in the region for various governments and businesses.
When did Kenya join the COMESA sugar safeguard?
Kenya initially sought the Sugar Safeguard at the launch of the COMESA Free Trade Area in 2001 under Article 61 of the COMESA Treaty. At the time, the country’s sugar industry required structured protection to undertake reforms.
The COMESA Council of Ministers governed the safeguard through strict benchmarks, including tariff-rate quotas, productivity investments, sector restructuring, infrastructure development, and continuous performance monitoring.
Kenya has fully met the obligations as it exits the safeguard to pursue competitiveness in the sugar industry.
“The conclusion of the safeguard therefore marks the successful completion of a reform cycle, not its abandonment. Kenya now enters a new phase defined by competitiveness, value addition, regional integration, and sustainable growth, supported by a clear policy framework and a restructured private-sector-led industry,” the CEO explained.
In light of the exit move, the government has stated that it remains fully committed to safeguarding farmer livelihoods, supporting miller viability, and ensuring food security, price stability, and long-term growth of the sugar sector within the COMESA Free Trade Area.
The sugar value chain
Chesire went on to explain that sugar is used in the manufacturing of various products around the world, processes that have significantly lowered the effective cost of sugar production.
“Value is realized through integrated processing of ethanol from molasses, electricity generation from bagasse supplied to national grids, paper and board manufacturing, industrial alcohols, and other downstream products. These practices significantly lower the effective cost of sugar production and explain why some exporting countries are able to supply sugar at comparatively lower prices.”
He stated that Kenya’s exit from the COMESA Sugar Safeguard comes even as the Kenya Sugar Board continues to support the diversification of sugar by-products in the country, which has improved financial benefits for millers and farmers.
“Supporting millers to diversify sugar by-products ensures stronger balance sheets, stable cash flows, and improved farmer payments. This approach not only strengthens millers but also insulates farmers from volatility associated with over-reliance on table sugar alone,” he added.
Overview of the Kenyan sugar industry
According to the Kenya Sugar Board, the country’s sugar subsector has recorded strong recovery and growth. Sugarcane acreage expanded by 19.4 per cent, from 242,508 hectares to 289,631 hectares.
This has been attributed to favourable rainfall patterns, improved access to certified seed cane, and targeted fertiliser subsidy interventions. These factors have caused an increase in sugar production by 76 per cent, from 472,773 metric tonnes in 2022 to 815,454 metric tonnes currently.
Presently, Kenya’s national sugar demand stands at approximately 1.1 million metric tonnes annually. However, Chesire stated that despite the improvements in the domestic sugar production, more time is needed to fully optimize operations in miller capacity expansion, factory rehabilitation, and newly leased mills.
Additionally, Kenya will continue to supplement local supply through imports from both the COMESA region and other approved sources while protecting local production.
“Population growth continues to drive demand, while surplus availability within the COMESA region is not always predictable. Importation from both COMESA and non-COMESA origins will therefore be applied in a controlled and transparent manner to ensure price stability for consumers, market certainty for producers, and overall food security,” he explained.
The way forward after Kenya exits the COMESA Sugar Safeguard
The Kenyan government has seen the long-term leasing of sugar mills in a bid to foster the efficiency and profitability of the companies.
Chesire stated that despite exiting the COMESA Sugar Safeguard, millers will still be supported through policy, predictable market access, and structured trade arrangements.
“The exit from the safeguard does not negate this support. On the contrary, it aligns with the reform trajectory already underway and reinforces certainty in the operating environment. The Kenya Sugar Board, under the Ministry, continues to provide strong regulatory oversight, market coordination, and farmer protection to ensure an orderly, fair, and sustainable industry.”
The Kenya Sugar Board is optimistic that the medium-term outlook for the sector remains strong, explaining that as miller capacity expands and farm productivity continues to improve, the country is projected to meet domestic demand and surpass self-sufficiency, positioning the country for surplus production and regional export competitiveness.



Discussion about this post